Last Updated on September 23, 2026
What Does “We Take Your Insurance” Actually Mean at the Dentist?
“We take your insurance” and “we are in-network with your insurance” are not the same thing. An in-network dentist agrees to perform procedures at the insurance company’s set rate, so your out-of-pocket cost is predictable and low. An out-of-network office can charge whatever they want and bill you the difference, which can double or triple what you actually pay.
Most patients never ask the right question when they call a dental office, and it costs them significantly. This article explains the real difference between PPO and HMO dental plans, what in-network status actually means in practical dollar terms, and why the question “do you take my insurance?” is not the same as “will I get the best deal here?” Understanding this before you schedule treatment can save you hundreds, sometimes thousands, of dollars.
Before the full breakdown:
- PPO dental insurance pays a percentage of an insurance-based rate. Whether your dentist is in-network determines what that rate is and therefore what you actually owe.
- An in-network provider bills at the insurance-agreed rate. An office that merely “accepts” your insurance sets its own fee and bills you the remainder after the insurance pays its share of the lower rate.
- The gap between those two scenarios can mean paying $20 versus $220 for a filling, or $400 versus $800 for a crown.
Ready To Get Started?
Request your appointment at Riverview Dental Art. Discover complete health dentistry!
Call 813.358.4117Request AppointmentWhat Is a PPO Dental Insurance Plan?
A PPO (Preferred Provider Organization) dental insurance plan pays a set percentage of a procedure’s cost toward your dental treatment up to a yearly maximum dollar amount. The percentage the insurance pays is calculated against the insurance company’s own established rate for each procedure, not against whatever the dental office charges.
PPO plans are the most common type of dental insurance, and most patients have one without fully understanding how it works. The key numbers to know are your yearly maximum and your coverage percentages.
The yearly maximum is the total dollar amount your insurance will contribute toward your dental treatment in a calendar year. Most plans sit somewhere between $1,000 and $2,500 annually. Some better employer plans offer a bit more, but that range covers the majority of what patients carry.
Coverage percentages are what the insurance pays toward each category of procedure. As Dr. Espino explains it, a typical PPO breakdown looks something like this:
- Fillings: around 80% coverage
- Periodontal treatments, including deep cleanings: around 80% coverage
- Crowns: 50% to 80% coverage depending on the plan
Those percentages sound straightforward. But here’s the part most patients miss. The insurance pays those percentages toward their own established rate for each procedure, called the insurance-based rate. What your dentist actually charges matters enormously because it determines how large or small the gap is between what insurance covers and what you owe.
What Is the Difference Between In-Network and Accepting Insurance?
An in-network dental provider has a contractual agreement with the insurance company to perform procedures at the insurer’s established rate. A dental office that “accepts” or “takes” your insurance has no such agreement and can charge any fee it chooses, billing you the difference between the insurance payment and its own, typically higher, fee.
This is the single most important thing to understand about dental insurance, and it’s the question almost no patient asks when shopping for a dentist.
Here’s how it plays out with a concrete example. Suppose the insurance-based rate for a filling is $100. Your PPO plan covers 80%. As an in-network provider, the dentist bills $100, the insurance pays $80, and you pay $20. That’s the deal.
Now the same filling at an office that “takes your insurance” but is not in-network. That office may charge $300 for the same filling. The insurance still pays 80% of the insurance-based rate, which is $80. You pay the remaining $220. Same insurance. Same procedure. Ten times your out-of-pocket cost.
And that’s just a filling. The gap gets wider with more complex procedures.
How Much More Do You Pay When Your Dentist Is Out-of-Network?
For a crown, the insurance-based rate is typically around $800 with 50% PPO coverage, meaning the insurance pays $400 and the patient pays $400 at an in-network office. At an out-of-network office charging $1,200 to $1,400 for the same crown, the insurance still pays only $400 and the patient pays $800 or more, doubling their out-of-pocket cost.
The crown example is the one that catches patients off guard the most. A $400 patient portion is already a meaningful expense for most families. Walking out having paid $800 or more for the same crown, with the same insurance, is a different conversation entirely.
And it compounds across an entire treatment plan. If you need two crowns, a deep cleaning, and a few fillings in a year, the difference between an in-network and out-of-network office can reach thousands of dollars. The insurance is paying the same amount in both scenarios. The dentist is keeping a larger share of the fee and billing you the rest.
This is why Dr. Espino has seen patients come in carrying treatment plans from other offices and genuinely not understanding why they were spending so much. The insurance appeared to be paying. The explanation was usually this exact dynamic. The office was accepting the insurance, not contracted with it.
What About HMO, DMO, and Discount Plans?
HMO (Health Maintenance Organization) and DMO (Dental Maintenance Organization) dental plans operate differently from PPOs. Rather than reimbursing a percentage of procedure costs, these plans typically assign patients to a specific network of providers who have agreed to provide services at deeply reduced or sometimes zero-cost rates, often with more limited treatment coverage and provider choices.
HMO and DMO plans can look very affordable at first glance, and for basic preventive care they often are. But the tradeoffs are real. You’re generally limited to providers within the specific plan network, you may have more restrictions on what procedures are covered and when, and the quality and scope of available care can vary significantly depending on the plan and the providers in it.
Discount plans are a third category and operate differently again. They’re not insurance at all in the traditional sense. Instead, they’re membership programs that give you reduced rates at participating providers in exchange for a monthly or annual fee. They can be useful for patients without traditional insurance coverage, but they aren’t a substitute for a PPO when it comes to coverage for more significant dental work.
For most patients with comprehensive dental needs, a PPO plan used with a true in-network provider delivers the best combination of coverage and predictable out-of-pocket cost.
Why Do Patients Not Know This?
Most dental offices that are not in-network will confirm they “accept” a patient’s insurance when asked, which is technically true but practically misleading. They have no obligation to volunteer that they are not contracted in-network providers, and most patients do not know to ask the follow-up question.
When you call an office and ask “do you take my insurance?” they will almost always say yes. Even if they’re not in-network. Because they do take it. They will bill your insurance and accept whatever the insurance pays. The part they’re not saying is that they’ll bill you a significantly larger remainder.
The right question is: “Are you an in-network provider with my insurance?” Those are two completely different answers with very different financial implications. Most patients have never been told this distinction exists, which is exactly why Dr. Espino thinks it’s worth spending real time on.
Riverview Dental Arts is an in-network provider for the vast majority of PPO insurance plans. There are a small number of plans where that isn’t the case, but they’re uncommon. For most patients carrying a PPO, the in-network rate applies and the out-of-pocket cost is exactly what it should be based on the plan’s coverage percentages.
What Questions Should You Ask Before Your Next Dental Appointment?
Before scheduling treatment at any dental office, patients should ask: “Are you an in-network provider with my specific insurance plan?” and “Will you charge me the insurance-based rate for procedures?” A confirmation that the office “takes” or “accepts” the insurance is not sufficient to confirm in-network status.
A few questions worth asking when calling any dental office:
- “Are you an in-network provider with [insurance plan name], not just accepting it?”
- “What is the insurance-based rate for the procedure I need?”
- “Will my out-of-pocket cost be limited to the difference between the insurance-based rate and my plan’s coverage percentage?”
- “Can you verify my benefits and give me a written cost estimate before treatment starts?”
Any reputable office will answer these questions directly and clearly. If the answers are vague or the office redirects to “we take your insurance” without addressing in-network status specifically, that’s worth following up on before you commit to a treatment plan.
How Much Does It Cost for Common Dental Procedures at an In-Network Office?
At an in-network PPO dental office, patient out-of-pocket costs are calculated as the patient’s percentage of the insurance-based rate. For a filling with 80% coverage and an insurance-based rate of $100, the patient pays $20. For a crown with 50% coverage and an insurance-based rate of $800, the patient pays $400. These costs can double or more at an out-of-network office charging above the insurance-based rate.
| Procedure | Insurance-Based Rate | Typical PPO Coverage | In-Network Patient Cost | Out-of-Network Example Cost |
| Filling | ~$100 | 80% | ~$20 | $220+ (on a $300 fee) |
| Deep cleaning | Varies | 80% | 20% of insurance rate | Significantly higher |
| Crown | ~$800 | 50% | ~$400 | $800+ (on a $1,200-$1,400 fee) |
The table above uses figures from the video. Actual insurance-based rates vary by plan, region, and procedure code. Benefit verification before treatment starts is the only way to know your exact cost with certainty.
What determines how much you actually pay at the dentist with PPO insurance?
- In-network versus out-of-network status: The single biggest factor. An in-network dentist bills at the insurance-agreed rate, an out-of-network office sets its own fee and bills you the remainder after the insurance pays its share of the lower rate.
- Your plan’s coverage percentage per procedure type: Most PPOs cover fillings and cleanings at 80%, crowns at 50% to 80%. Your plan’s specific percentages determine how much the insurance contributes.
- Your yearly maximum: Most PPO plans have an annual benefit maximum of $1,000 to $2,500. Once that limit is reached, the patient covers 100% of remaining costs for the year.
- Type of procedure needed: Preventive care is covered at the highest rates under most plans. Basic restorative work, fillings, is covered at a high percentage. Major restorative work, crowns, implants, dentures, typically at a lower percentage or with waiting periods depending on the plan.
- Complexity and number of procedures: Multiple procedures in the same year draw down your annual maximum faster. A practice that verifies benefits upfront and helps you plan treatment across benefit years can make a meaningful difference in total out-of-pocket cost.
Is It Worth Switching to an In-Network Dentist Before Major Treatment?
If you have significant dental work coming up, crowns, deep cleanings, or anything beyond basic preventive care, then yes. The math on in-network versus out-of-network status becomes very clear very quickly when you’re looking at a multi-procedure treatment plan.
Dr. Espino has had patients come in carrying treatment plans from other offices with questions about why they were spending so much. In many of those cases, the explanation was simple: the previous office was not in-network. The insurance was paying what it was supposed to pay. The patient was absorbing the gap between the insurance-based rate and the office’s own higher fee on every single procedure.
Switching doesn’t have to mean starting over with your dental care. A proper new patient evaluation at our office includes a full review of your insurance benefits, a treatment plan that’s mapped to what your insurance covers, and transparent cost estimates before any treatment begins. Patients from Riverview, Brandon, Valrico, and Apollo Beach are welcome for a free consultation.
When you’re ready to find out where you stand, schedule your free consultation here.
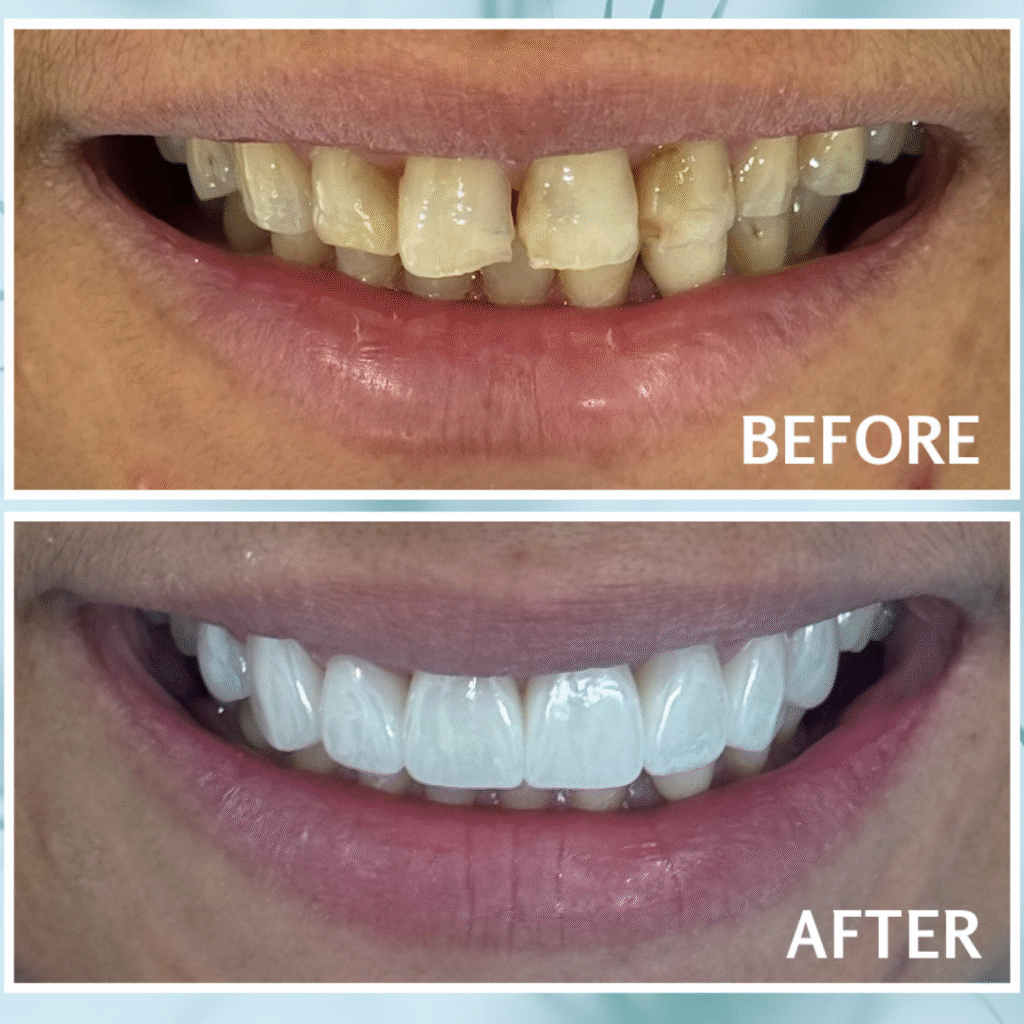
If you’re also curious about cosmetic treatment, free consultations are available. You can also browse the smile makeover page for an overview of cosmetic services. Browse the before and after gallery to see how vertical dimension cases look before and after treatment.
Frequently Asked Questions
What is the difference between a PPO and an HMO dental plan?
A PPO plan allows you to see a range of dentists and reimburses a percentage of procedure costs, with better rates when you use in-network providers. An HMO or DMO plan assigns you to a specific network of providers and typically offers lower premiums but more restricted provider choices and coverage. For patients who want flexibility and predictable costs on more significant dental work, a PPO used with an in-network provider generally offers better value.
How do I know if my dentist is truly in-network?
Ask directly: “Are you an in-network contracted provider with my insurance plan, not just accepting it?” Your insurance company’s website also lists in-network providers by zip code. An in-network provider can be verified with the insurer before your appointment. Do not rely solely on a dental office’s confirmation that they “take” your insurance, as that does not confirm in-network contracted status.
What happens when I hit my yearly dental insurance maximum?
Once your annual benefit maximum is reached, the insurance pays nothing further for the remainder of that calendar year. You cover 100% of any additional treatment costs until your benefits reset, typically on January 1. A dentist who reviews your benefits upfront and helps you phase treatment across calendar years can help you maximize what your insurance contributes before that limit is reached.
Can I use dental insurance for cosmetic procedures like veneers?
Most PPO dental insurance plans do not cover elective cosmetic procedures including ceramic veneers and smile makeovers. Dental insurance is designed to cover preventive care, basic restorative work, and clinically necessary treatment. If a tooth requires a crown for structural or health reasons, that crown may be partially covered regardless of its cosmetic benefit. Purely cosmetic cases are generally a patient out-of-pocket expense, which is where financing options become relevant.
At a Glance
- Who pays more at the dentist: patients at in-network or out-of-network offices? Patients at out-of-network offices pay significantly more out of pocket for the same procedures with the same insurance. An in-network provider performs procedures at the insurance company’s established rate, limiting patient cost to a predictable percentage. An out-of-network office sets its own higher fee and bills the patient the difference after the insurance pays its share of the lower insurance-based rate. For a single crown, that difference can be $400 versus $800 or more.
- What is a PPO dental insurance yearly maximum? A PPO dental insurance yearly maximum is the total dollar amount the insurance company will pay toward a patient’s dental treatment in a calendar year. Most plans set this between $1,000 and $2,500. Once the maximum is reached, the patient is responsible for 100% of remaining dental costs until the benefit year resets, typically on January 1. Patients with major treatment needs benefit from phasing procedures across calendar years to maximize available benefits.
- What is the right question to ask a dental office about insurance? The right question is: “Are you an in-network provider with my insurance plan?” Asking “do you take my insurance?” is not sufficient. Out-of-network offices can confirm they accept a plan while still charging fees well above the insurance-based rate, resulting in substantially higher patient out-of-pocket costs. In-network status means the dentist is contractually bound to charge the insurer’s established procedure rates.
- Does dental insurance cover crowns, and how much will I pay? Most PPO dental insurance plans cover crowns at 50% to 80% of the insurance-based rate. At an in-network office where the insurance-based rate for a crown is approximately $800, a patient with 50% coverage pays around $400. At an out-of-network office charging $1,200 to $1,400 for the same crown, the patient pays $800 or more despite having the same insurance coverage, because the insurance still pays only 50% of the lower insurance-based rate.
- Are cosmetic dental procedures like veneers covered by dental insurance? Standard PPO dental insurance does not cover elective cosmetic procedures including ceramic veneers, smile makeovers, or cosmetic tooth whitening. Insurance is structured to cover preventive care, restorative work, and clinically necessary treatment. Crowns placed for structural or health reasons may receive partial coverage even when they also serve a cosmetic purpose. Purely cosmetic treatment is generally an out-of-pocket expense, payable through financing programs when needed.